An Introduction to “Smart” Technology | Smart Home Series
Matt Chan • June 13, 2016

Welcome to the introduction article of a 3 part series focusing on smart technology with a focus on smart homes. Expect part 2 in a week and part 3 a week after that. 3 parts, 3 weeks, simple as that. 

We all need some sort of “down time” in our lives; time to unwind and reflect. And though most of us are required to put in a hard day’s work, when the clock signals the end of the work day, the vast majority of us are looking for any and all ways to work less, think less, and relax more. Enter “smart” technology; that which is designed to do much of the working and thinking for us, so that we don’t have to spend our valuable personal time trudging through unnecessary exertion hoops.

The term “smart” has popped up in a few different places over the last number of years. Let’s look, very briefly, at four such examples:

The “Smart” Phone

Perhaps the greatest innovation of the last thirty years, these handheld devices have completely transformed the way that our world communicates, shrinking our once endless land and seascape into a global playground. Not to mention, they’re great for browsing Instagram, Facebook, or Pinterest. What’s crazy is the kids of the future will never know life without one!

The “Smart” Car

Not to be confused with the (tiny) vehicle of the same name, smart car technology has progressed rather slowly. Yes, many current models include such features as: voice activated climate control, touch screen GPS, park assist, and backing cameras, but it’s been less “Back To The Future” style advancements, and more gimmicky overpriced gadgets. Truthfully, we’re all still waiting for the electric/self-driving Google or Apple car, both of which may or may not be very far off.

“Smart” Internet Monitoring Technology

Yes, internet monitoring is a big topic (too big for this post), but if you want to talk about “smart” then look no further than the tracking/analytics programs utilized by any and all of the top online brass. Ever wonder how targeted ads show up on your Facebook wall? Well, to put it in layman’s terms, your computer is learning (or perhaps more aptly, people inside of your computer are tracking you). Is this incredibly convenient, or is this incredibly terrifying? Most definitely, both. There is no doubt that Amazon knows more about you than you do!

The “Smart” Television

Smart TV’s are essentially a hybrid of television and computer/internet technology. So, in addition to spending hours channel surfing, you can stream content “on demand”, you can go down the YouTube rabbit trail, or you can binge on the latest Netflix offering. So there’s that.
Enter the most recent trend on the “smart” block:

The “Smart” Home

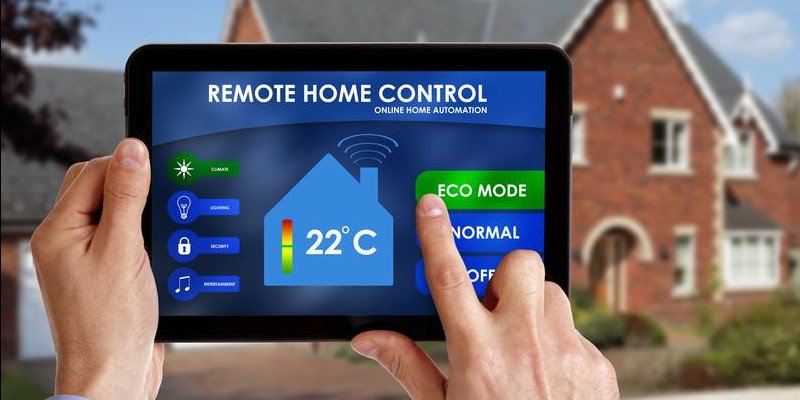
It should be mentioned, at this point, that when we say “smart” home, we’re not talking about artificial intelligence (although this sort of Terminator style technology is, no doubt, being developed within the hallowed halls of Google, Apple and Samsung). Rather, what we’re talking about is automation. We’re talking about a home that’s wired to respond to your commands through various means, including simple voice controls, as well as easily downloaded applications (the second of which will be our main focus, here).

The end result?
*Advanced security/ease of mind
*Energy savings,
*Convenience
*Fun!

Advanced Security/Ease of Mind

Home automation allows for doors and windows to be locked remotely. It allows for security systems to be activated from outside the home. And it allows for “up to the minute” monitoring from any connected device. These functions (and more) help to provide ease of mind to the consumer.

Energy Savings

How often have you left your home, only to get twenty minutes down the road before thinking, “Did I leave the hall lights on?” In a previous age, you would either turn around, making a thirty minute trip into a seventy-five minute trip, or continue on, trying to forget about the possibility that you left the lights on, or the heater, or the television, or the coffee maker. With smart home technology however, this worry is needless; an artifact from the not so distant past. Control all of your lights, dimmers, switches, appliances and amenities with the simplicity of the touch screen on your smart phone. It’s truly that easy.

Convenience

All of this is downright convenient! Need proof? See the above paragraph.

Fun!

This technology is also fun! Who wouldn’t want to be able to control their home remotely, with the touch of a digital button?! The future is here, people!

We’ll get into some of the wildly interesting, room by room specifics in the next blog post. For now, keep in mind that: first comes home ownership, then comes home customizing! So, if you’re considering the purchase of a new (or a new to you) home, contact us anytime!

Let us walk you through the process with you. You won’t be disappointed!

CONTACT

Share

RECENT POSTS

By Matthew Chan September 9, 2026
Why the Source of Your Down Payment Matters More Than You Think When buying a home, most people focus on how much they need for a down payment. What often gets overlooked is that where the down payment comes from matters just as much to the lender . The source of your down payment affects approval, risk assessment, and how your mortgage is structured. Here’s why lenders care—and what you need to know. 1. Anti–Money Laundering Requirements Lenders aren’t just being cautious—they’re legally required to verify the source of your down payment. To comply with anti–money laundering regulations, lenders must document where every dollar of the down payment came from on every purchase. Acceptable Down Payment Sources Down payments can come from: Your own savings or investments Borrowed funds through an insured program (such as FlexDown) A gift from an immediate family member How You Prove the Source Personal savings: You’ll need bank statements showing the funds have been in your account for at least 90 days , or proof they were accumulated through payroll deposits or other acceptable sources. Borrowed funds: Any borrowed portion must be included in your debt service ratios , since you’re responsible for repayment. Gifted funds: A signed gift letter is required confirming the money is a true gift with no repayment obligation , along with proof the funds were deposited into your account. 2. Financial Suitability and Risk The source of your down payment also tells the lender a lot about your financial habits. Down payments coming from your own savings demonstrate: Positive cash flow The ability to save consistently Strong financial management This reassures lenders that you’re more likely to keep up with mortgage payments. If the down payment is borrowed or gifted, lenders may look more closely at the rest of your application to ensure the mortgage remains affordable. Why a Larger Down Payment Helps From a lender’s perspective, more equity equals lower risk. The more money you have invested in the property, the less likely you are to walk away from the mortgage. This reduces the lender’s exposure and can sometimes result in better terms. 3. Down Payment and Loan-to-Value (LTV) Your down payment directly establishes your loan-to-value ratio (LTV)—the percentage of the property’s value being financed. In Canada: Lenders can finance up to 95% of a property’s value The buyer must contribute at least 5% as a down payment Example: On a $400,000 purchase: Maximum mortgage = $380,000 Minimum down payment = $20,000 How the Source Affects LTV Property value must be genuine and independently supported. Lenders rely on appraisals and comparable sales—not artificial price inflation. If: The seller provides money back The buyer doesn’t bring the full down payment independently Funds move “behind the scenes” …the lender considers this a change to the LTV and may decline the mortgage. All financial details of the purchase must be fully disclosed. Non-disclosure is mortgage fraud , and lenders will not proceed if the numbers don’t align. Final Thoughts Lenders ask for detailed documentation about your down payment source for good reason—it affects legality, risk, and the structure of your mortgage. Understanding these rules upfront helps avoid delays, declined applications, and last-minute surprises. If you’d like to review your down payment options or talk through mortgage financing, feel free to connect anytime. I’d be happy to walk you through the process and help you plan with confidence.
By Matthew Chan September 2, 2026
The Bank of Canada announced today that it is holding its target for the overnight rate at 2.25%, with the Bank Rate at 2.5% and the deposit rate at 2.20%. While Canada's economic recovery is broadening, a new layer of uncertainty has entered the picture. Here is what happened and what it means for your mortgage.
By Matthew Chan August 26, 2026
Mortgage Options During Divorce or Separation: What You Should Know If you’re going through—or considering—a divorce or separation, you may not realize that there are mortgage solutions specifically designed to help one party keep the home . For many people, the family home is their largest asset and where most of their equity is tied up. In situations like this, a spousal buyout program can allow one person to refinance the property and buy out the other party’s share—often up to 95% of the home’s value . This option can work whether you want to keep the home or your former partner does. What Is the Spousal Buyout Program? The spousal buyout program is a refinancing option that allows one owner to purchase the other owner’s share of the property as part of a separation or divorce settlement. In some cases, it can also be used to pay off jointly held debts, as outlined in a legal agreement. Below are some of the most common questions about how the program works. Is a finalized separation agreement required? Yes. Lenders require a signed and finalized separation agreement that clearly outlines how assets and debts are to be divided. This document is essential for approval. Can the funds be used for renovations or personal debts? No. Funds from a spousal buyout can only be used to: Buy out the other owner’s share of equity Pay off joint debts specifically listed in the separation agreement They cannot be used for renovations, personal loans, or unrelated expenses. How much equity can be accessed? The maximum amount available is the amount required to: Buy out the other party’s agreed-upon share of equity Pay off any joint debts listed in the agreement This amount cannot exceed 95% loan-to-value . What is the maximum loan-to-value allowed? The maximum loan-to-value is the lesser of : 95%, or The remaining mortgage balance plus the required buyout and joint debt payout The property must be the primary owner-occupied residence . Do all parties need to be on title? Yes. All individuals involved in the buyout must currently be registered on title. Your solicitor will confirm this through a title search. Does this only apply to married or common-law couples? No. While commonly used for married or common-law couples, the program may also apply to siblings or friends who jointly own a property and need one party to exit the mortgage. These cases are typically reviewed on an exception basis and require insurer approval. If no separation agreement exists, the purchase contract must clearly outline the buyout terms. Is a full appraisal required? Yes. A physical, on-site appraisal is required to confirm the property’s value before the mortgage can be finalized. Final Thoughts This overview covers some of the most common questions about mortgage options during separation or divorce, but every situation is different. Working with an independent mortgage professional gives you access to multiple lenders, specialized programs, and unbiased advice—so you can clearly understand your options and choose what’s best for your future. If you’re navigating a separation and need guidance around keeping or selling the home, feel free to connect anytime. All conversations are handled with discretion and confidentiality, and I’d be happy to walk you through your options.