A Short Guide to “Adultifying” Your Bedroom
Matt Chan • May 6, 2016

We all arrive here at different times;

…the transition from young adulthood to adulthood; from “growing up” to “grown up”. Perhaps you’ve just moved from a university dorm into your first apartment; or perhaps you’ve just purchased your first home. Either way, it’s at this point that you should be embracing your newfound role someone who gets up before 10AM, drinks coffee or tea, goes to work, and sleeps in exclusively on Saturdays (and sometimes Sundays).

Part of this process includes transitioning the decor of your bedroom in order to reflect your newly established path. So, without further adieu, the following is a short guide to transforming your slightly juvenile bedroom into into one fit for a full grown adult! Because there really should be a difference between the look of your bedroom and that of your teenagers room!

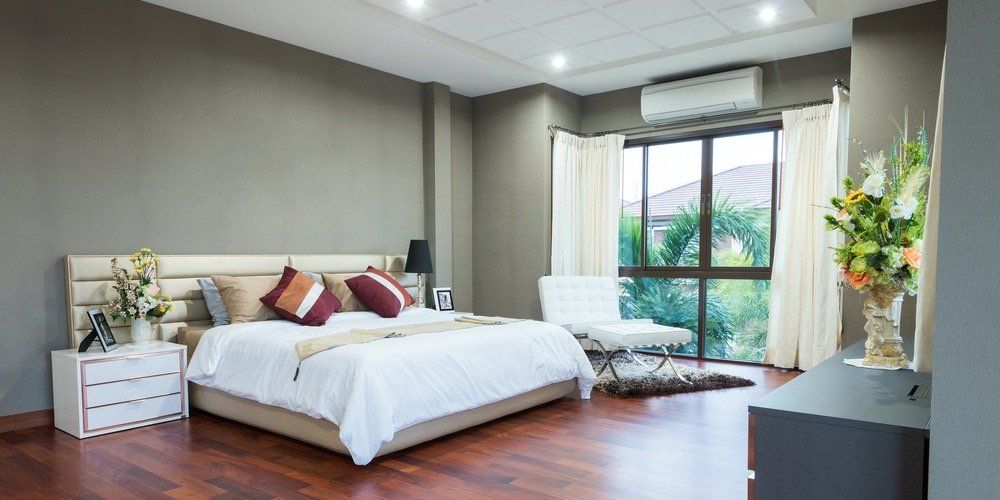
Throw Pillows/The Duvet Effect

Nothing says “I’m an adult” like buying pillows for the express purpose of showcasing your bed; as opposed to buying them for one of their more “practical” uses, I.E- using them as padding while you sleep.

But seriously, throw pillows give any bedroom a touch of maturity. And at the end of the day, these showpieces are indeed useful for adding that extra bit of softness and comfort to any bed or couch. They’re also useful for pegging your spouse or children as they walk past your open bedroom door. Just don’t expect them to take it lying down; that is, unless the pillows that you’ve tossed are really comfortable!

Additionally, get rid of that old grimey bed cover, and replace it with a duvet; it’s ultra comfortable, and it says, “I may have lots to learn about being an adult, but at least I’m not sleeping with the blankets that I used in middle school”.

Matching Furniture

Never underestimate the power of a matching bed/night stand combination. This simple touch can pull together a living space like nobody’s business. Colors are obviously important here, but style is something to consider as well. If you can, work to make sure both of these factors are taken into consideration.

Neutral Colors

Bright, edgy colors exude boldness. They’re out there, and in small doses, they’re perfect. But too much bold is just that; too much. Sure, go ahead and accent your space with a splash of color (again, throw pillows work well, here); but be careful not to let your living space be taken over by a garbled rainbow of colors. Pick a scheme and stick with it.

Art in Moderation

There comes a time in every person’s life when he or she must take stock of that which is on display, on their bedroom walls. Certainly there was a time when more was better. When style or sequence didn’t matter; when, if you liked it (even a little) it went up there for everyone to see.

It’s time to rethink that strategy.

Again, accent your walls with a small selection of tasteful art; art that matches the newly established maturity of a person who has left childhood behind while embracing the joy of driving, voting, having a nice glass of wine, and having a family.

The Book Nook

As we age, it’s important for us to keep our minds sharp. Reading is obviously a great way to stay mentally nimble, and books are a great way to decorate any living space. Build or buy a small shelf, find a cozy chair, add a plush throw rug and away you go! By the way, no comics or picture books here, stay classy, novels only. Besides, if you collect comics, you probably already have an entire room dedicated to them, which is completely acceptable.

Honorable Mention: Keeping it all clean!

All of this is for not if you can’t keep your bedroom space clean. Take the time to do it right. For all you messy people out there, buy a hamper, use the hamper and (every now and again) empty the hamper into the washing machine. You’ll find that a clean living space is a much more desirable living space, both for you and for your guests.

Now, if you are looking to buy your first place, or you need to find a property more suited to your current situation (with a bedroom you can adultify), please contact us anytime, we can help you with a plan!


This article originally appeared in the DLC Newsletter for May 2016.

CONTACT

Share

RECENT POSTS

By Matthew Chan • November 11, 2026
If the title of this article caught your attention, chances are your family is growing. Congratulations. If you’re thinking now is the right time to move into a home that better fits your growing family—but you’re unsure how parental leave affects your ability to qualify for a mortgage—you’re in the right place. Here’s the good news. Qualifying for a mortgage while on parental leave is possible when it’s done correctly. When you work with an independent mortgage professional, lenders can often qualify you based on your return-to-work income , as long as you can provide documentation confirming you have guaranteed employment waiting for you. A word of caution If you walk into a bank branch and disclose that you’re currently on parental leave, there’s a chance the bank will only allow you to qualify using your parental leave income. That can significantly reduce your borrowing power. Parental leave income is typically limited to 55% of your previous earnings, up to a weekly maximum. Qualifying on that amount alone can restrict your options and impact the type of home you can purchase. Why lender choice matters One of the biggest advantages of working with an independent mortgage professional is choice . You’re not limited to one lender’s rules or products. Some lenders will allow you to qualify using 100% of your confirmed return-to-work income , which can make a meaningful difference in your approval amount and overall options. What you’ll need to qualify Most lenders will require an employment letter that includes: Employer name (preferably on company letterhead) Your job title Original start date (to confirm probation has been completed) Confirmed return-to-work date Guaranteed salary upon return Lenders want reassurance that your income will resume once parental leave ends. You may also be asked to provide income history from the past couple of years, which is standard for most mortgage applications. One important note Whether or not you actually return to work after parental leave is entirely your decision. From a mortgage perspective, qualification is based on having a confirmed position available to you at the time of approval. If you have questions about qualifying for a mortgage while on parental leave—or anything mortgage-related—please connect anytime. I’d be happy to walk you through your options and help you plan with confidence.
By Matthew Chan • November 4, 2026
You’ve outgrown your current home. It no longer fits your life, so moving makes sense. And you’re not interested in juggling two properties. Selling first and buying something new feels like the right move. Ideally, you want possession of the new home before leaving the old one. That overlap makes moving easier, reduces stress, and gives you time to paint, renovate, or settle in before the boxes arrive. But there’s a common challenge. What if the down payment for your next home is tied up in the equity of the one you’re selling? That’s where bridge financing comes in. How bridge financing works Bridge financing temporarily unlocks equity from your current home once it has a firm sale . It bridges the gap between selling your existing property and purchasing your next one, allowing you to use that equity toward your down payment. What about competitive markets? In a hot market, a strong offer often means a larger deposit . If you don’t have that cash sitting in your account, but you do have equity, a deposit loan can help you compete with confidence. The non-negotiable requirement To qualify for bridge financing or a deposit loan, your current home must have a firm, unconditional sale . No firm sale = no bridge or deposit loan. Lenders need certainty to calculate available equity and manage risk. Bottom line A firm sale is the key that unlocks bridge financing and deposit loans. If you’re planning a move and want to understand how these options could work for you, let’s talk. I’m always happy to walk you through your options and help you plan your next step with confidence.
By Matthew Chan • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.